credolab -
Approve more.
Risk less.
Add behavioural insights to your existing lending workflow without changing your decision engine.




We are the scoring partner everyone wants, but not everyone wants to talk about. While these brands are proud to be public, many of our largest global clients prefer to keep their “unfair advantage” a secret. We do not mind; we are proud to be the power behind their “Yes.”
Number of Underserved Adults
Sound familiar?
lack of GOOD data?
If you are:
- Forced to reject too many applicants
- Rejecting high-risk and false positives
- Trapped in a cycle of data asymmetry
You are in the right place.
We are here to help you separate "no data" from "bad risk" and approve more creditworthy applicants with better alternative data for credit scoring.
Why we work
THE Behavioural edge
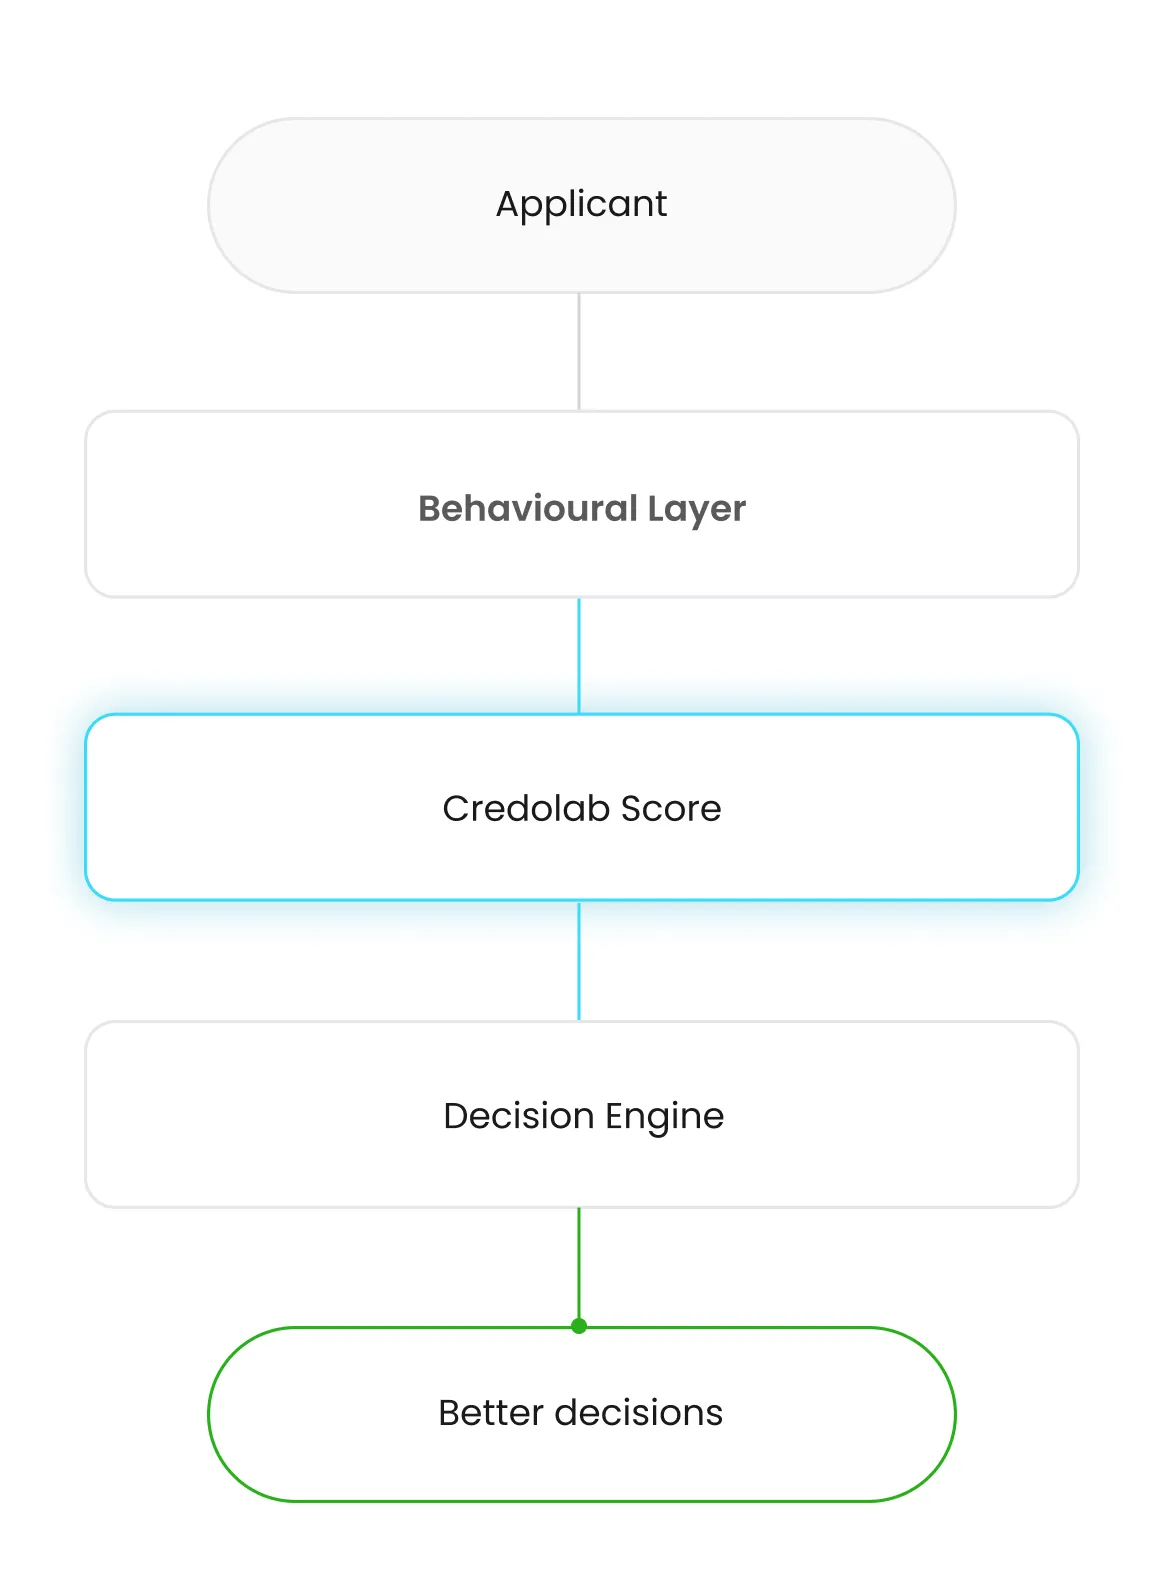
Integrate a layer of superior signals into your existing credit risk models and credit scoring solutions. Identify risk and intent in real time, with zero PII and for 100% of your applicants.
- Boost predictive power by up to 45%: Add high-definition behavioural signals through alternative credit scoring and real-time credit data solutions to distinguish your creditworthy borrowers from high-risk applicants.
- Increase approvals by up to 32%: Identify "hidden gems" in thin-file and no-file segments without touching your risk appetite.
- Reduce defaults by up to 50%: Flag high-risk behavioural patterns early and stop bad debt before it hits your books.
We take your data as seriously as you take your risk.
- ISO/IEC 27001 certified: Internationally recognised standards for information security.
- Encrypted: The metadata is protected at rest and in transit.
- Privacy compliant by design: We operate under a strict Data Processor Agreement. We collect data only after an explicit opt-in is received. No consent, no collection. Period.
Proven across 37 countries.
Calibrated for yours.
Traditional data stops at the border; behavioural intelligence adapts to it.
We apply behavioural patterns from our alternative credit scoring platforms, learned across 37 countries, to give you an immediate, locally calibrated advantage, wherever you lead.






Approval rate
Gauge our compatibility
Built to fit
A modular risk solution that fits into your existing workflow permanently. Not the other way around.
- Multi-layered protection: Choose the insights you need, when you need them. From alternative risk scores to insights that serve as defensive layer or power marketing segmentation.
- Seamless experience: Invisible to the user, configurable to your stack, and indispensable to your risk team and credit scoring platform.






Stop guessing. Start SCORing.
Why leave your growth to chance when you can lead with intelligence? Join the world’s most innovative lenders and turn behavioural scores into your biggest competitive advantage.
Frequently Asked Questions
What is Credolab?
Credolab is a data science and behavioural risk scoring company. It predicts the probability that a credit applicant will miss a payment, using proprietary device and behavioural interaction metadata collected with the applicant's permission.
Banks, neobanks, BNPL providers and digital lenders add our scores to the decisioning they already have, so they approve more creditworthy applicants and fewer bad ones. Since 2016 we have scored more than 200 million people across 37 countries. We are proud to be the power behind their "Yes".
How is Credolab different from a credit bureau?
Credolab complements the credit bureau; it does not replace it. The bureau tells you whether an applicant has paid in the past. We tell you whether they intend to repay, based on how they behave during the application.
Our score typically correlates less than 5% with bureau, cashflow and socio-demographic data, so it adds new signal instead of repeating what you already know. We also score the applicants the bureau cannot see. We are not a credit bureau; we work alongside bureaus as a partner. Their data looks back; ours reads intent.
What data does Credolab use to score applicants?
Credolab uses privacy-consented device and behavioural interaction metadata, never personal data or credit history. Our SDK can collect up to 80,000 data points, such as how an applicant completes the application form, device settings and usage patterns like battery charging habits.
We look at counts and patterns, never content: no messages, no photos, no names. The SDK only uses the permissions your app already has, and still delivers a predictive score when sensitive permissions are denied. We read the behaviour, not the person.
Who uses Credolab?
Credolab is used by banks, neobanks, BNPL providers, credit card issuers and digital lenders that need to score applicants at the point of application. You can also get our scores through partners, including credit bureaus and decisioning platforms such as the FICO Platform, Provenir, Synapse Analytics, Taktile and TaranDM.
Our typical clients are growing into thin-file or no-file segments, or losing money to applicants who pass every fraud and ID verification check but never repay. Many prefer to keep their "unfair advantage" quiet, and we don't mind.
Our credit bureau hit rates are low. How can we grow without them?
Credolab scores 100% of your applicants, including those with no credit history. Anyone who applies on a smartphone or online leaves a behavioural footprint, and we turn that footprint into a predictive score. Your risk team gets a consistent signal from day one, for every applicant. No bureau file doesn't mean no data, and it doesn't mean bad risk.